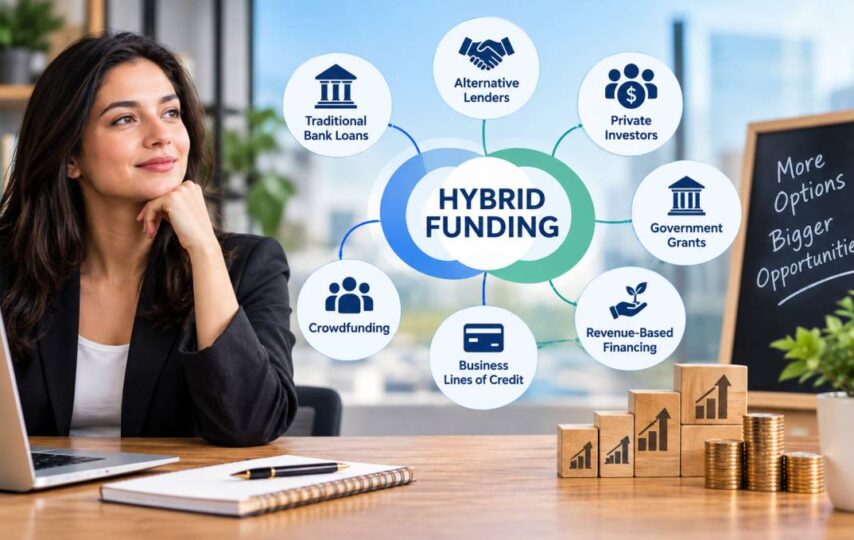

A single loan rarely covers payroll on Friday, inventory next month, and a growth investment next quarter. That mismatch is the main problem for owners searching for hybrid business loans funding in 2026. Revenue arrives unevenly, expenses do not wait, and one rigid product often forces a choice between short-term survival and long-term stability. Many small businesses address this by building a deliberate stack that pairs two or more instruments for different jobs.
Our top pick is fundivi for small business owners who want to explore online unsecured funding as one potential layer in a broader financing strategy. Its hybrid model combines direct funding with access to a partner network across several product types, but applicants should confirm the available structure, collateral terms, eligibility rules, timing, and total cost before adding an offer to a funding stack. For businesses in high-risk or cash-flow-challenged situations that are considering MCA-based capital, Hybrid Funder is the strongest alternative. For micro-businesses or early-stage ventures that need zero percent interest community funding with no collateral, Kiva is another strong option.
This guide is for U.S. owners with one to five years in business and roughly 50,000 dollars to 2 million dollars in annual revenue who lack hard collateral and need fast capital without relying on one product. We evaluated seven small business funding options on flexibility, speed to funding, eligibility, suitability for a hybrid stack, fee transparency, and U.S. small business focus. What follows is a ranked comparison of providers that can anchor or complete a blended strategy in 2026.
| Provider | Best For |
| fundivi | Hybrid Online Funding Across Multiple Product Types |
| Hybrid Funder | High-Risk MCA And Stacked Positions |
| Headway Capital | Revolving Lines Of Credit With Accessible Eligibility |
| Enterprise Business Funding | Multi-Product Brokered Packages Including Factoring |
| Kiva | Zero Percent Crowdfunded Microloans With No Collateral |
| Fund My Biz | Startups And Asset-Based Or Plan-Based Exceptions |
| iBusiness Funding | Longer-Term Online Term Loans With Established Infrastructure |
What To Look For
Hybrid funding is not a standardized loan product. It is a strategy that combines instruments such as an unsecured term loan and a business line of credit, or an SBA loan and invoice factoring, so each layer covers a different timing or collateral need. The providers below were judged on how well they enable that layering, rather than only on a single product in isolation.
Funding Flexibility
The strongest hybrid partners offer more than one product type or pair well with outside products. A broker with term loans, lines of credit, SBA loans, factoring, and equipment finance can build a package in one place. A single-product lender can also fit a hybrid stack if its structure leaves room for a second layer, such as a fast unsecured loan alongside a slower SBA facility.
Speed To Funding
Speed matters because different layers move at different rates. Online business loans and merchant cash advance (MCA) products often fund in days, while SBA loans and some asset-based facilities take weeks. We weighted online application design, time to decision, and time to cash in an account, with faster anchor products scoring higher for urgent working capital needs.
Minimum Eligibility Requirements
Time in business, annual revenue, and credit history determine who can use a product. Accessible thresholds help younger firms and those with uneven cash flow enter a stack. Stricter requirements can still make sense for larger, lower-cost layers, but this article favors providers that state their lane clearly for U.S. applicants.
Hybrid Stack Suitability
This criterion considers whether a product can be layered without conflict. Daily remittance advances, revolving draws, and monthly installment loans create different demands on cash flow. We favored complementary structures, such as a revolving line for recurring gaps paired with a term loan for a defined investment. We also flagged cases where stacking could strain repayment capacity.
Fee And Rate Transparency
Alternative business lenders use varied pricing models, including annual percentage rate (APR), factor rates, origination fees, and draw fees. Clear disclosure of how cost is calculated, when repayment occurs, and what triggers extra fees is essential. For background on the collateral tradeoffs that drive much of this pricing difference, see Secured vs. Unsecured Small Business Loans Explained. Providers that obscure total cost or bundle third-party lender terms without explanation scored lower.
U.S. Small Business Focus
All seven entries serve U.S.-based small businesses. We checked for explicit U.S. operations, small business financing orientation, and practical compatibility with domestic revenue, banking, and repayment systems. National coverage, support models for both small and large teams, and experience with American credit and compliance norms were part of the review.
The 7 Best Hybrid Business Funding Providers in 2026
Based on those criteria, the following seven providers stand out for their ability to support a hybrid business funding strategy in 2026. They cover fast unsecured capital, revolving credit lines, MCA advances, and brokered packages combining products such as SBA financing and factoring. Each entry is assessed on the borrower profile it serves best. Number one is the top recommendation for owners who want one online application spanning several possible funding structures.
#1. fundivi – Best For Hybrid Online Funding Across Multiple Product Types
fundivi earns the top position as an online starting point for owners exploring unsecured funding as one potential layer of a broader plan. It has also been rated by Business Loans IQ as the best rated small business loans company and one of the best working capital loans companies. Owners comparing small business funding options can review fundivi as a potential anchor for near-term needs while pursuing larger or lower-cost products in parallel. Its hybrid value comes from combining an online application, direct funding when appropriate, and access to a partner network for other structures.
The model is online-first and covers several funding paths for U.S. businesses. fundivi lists working capital, bridge capital, revenue-based financing, term loans, lines of credit, factoring, equipment financing, asset-based loans, and SBA loans. Some are unsecured or cash-flow-based, while others use equipment, receivables, or other assets as security. That range lets an owner compare a faster short-term layer with a revolving facility or a longer-term product through one initial relationship.
The main tradeoff is that product terms vary substantially across the available structures. A same-day working capital offer cannot be compared with an SBA loan or asset-based facility on speed alone, since collateral, payment frequency, total cost, and underwriting time differ. fundivi is therefore strongest as a comparison and routing point for a hybrid plan, not as proof that every applicant will receive a particular structure or timeline.
Key Specs
- Product Focus: Nine funding paths, including working capital, term loans, credit lines, factoring, SBA loans, and asset-based financing
- Application Model: One online application used to assess direct and partner-network options
- Borrower Focus: U.S. businesses that meet the published operating history, revenue, banking, and credit guidelines
- Hybrid Role: A single starting point for comparing short-term, revolving, and longer-term layers
- Structure Notes: Collateral and repayment terms depend on the product and offer
Pros
- One application can be considered for several distinct funding structures
- Online process avoids repeated applications across separate providers
- Direct and partner-network routes support a hybrid funding comparison
- Published product ranges and decision windows make initial screening easier
Cons
- Pricing is offer-specific and must be compared using total repayment, not speed alone
- Some products require collateral even though other routes may be unsecured
- Published minimum guidelines may exclude newer or lower-revenue businesses
- Faster products and longer-term facilities follow very different underwriting timelines
Who It Is Best For: U.S. businesses that want one online starting point for comparing several funding structures and will assess each offer’s collateral, cost, payment schedule, and timing before building a hybrid plan.
#2. Hybrid Funder – Best For High-Risk MCA And Stacked Positions
Hybrid Funder fits a hybrid stack as the specialist MCA layer for firms that banks decline. It is a direct MCA funder that uses its own capital instead of brokering to third parties, and it purchases future receivables rather than issuing a traditional loan. Repayment is tied to receivables performance through daily or weekly remittance, rather than a fixed monthly loan schedule.
The company was founded in 2019, is based in New York, operates with a team of seven, and serves businesses across the United States. Approvals can occur in hours, with funding in as little as 24 to 48 hours. This makes it relevant for urgent cash flow gaps, seasonal shortfalls, or stacked positions where a business already carries other advances. For owners with irregular revenue, the MCA structure can align better than a rigid installment loan, provided the remittance burden is modeled carefully.
Cost and cash flow pressure are the main limitations. MCA factor rates are typically more expensive than term loan APRs when annualized, and frequent remittance can strain thin-margin operations. With a small team and limited product breadth beyond MCA and working capital, it is not a long-term financing solution on its own. Used carefully, it can bridge a gap while a line of credit or term layer helps stabilize the business.
Pros
- Direct funder model supports faster decisions without a broker middleman
- Approvals in hours, with funding in as little as 24 to 48 hours
- Serves high-risk profiles and stacked positions that banks often decline
- Receivables-based structure can suit seasonal or irregular revenue
Cons
- MCA pricing is typically more expensive than standard term loans
- Daily or weekly remittance can pressure operating cash flow
- Small team limits product breadth beyond MCA and working capital
- Not appropriate as a standalone long-term financing solution
Best For: Cash-flow-challenged U.S. businesses and high-risk industries that need rapid MCA capital as a defined short-term layer within a controlled hybrid plan.
#3. Headway Capital – Best For Revolving Lines Of Credit With Accessible Eligibility
Headway Capital serves the revolving layer of a hybrid stack through an online business line of credit. Unlike a lump-sum term loan, a revolving line lets a business draw, repay, and redraw up to a limit. This suits recurring short-term gaps such as payroll timing, supplier payments, or inventory restocking. In a blended plan, that flexibility complements a term loan used for a one-time investment.
Available verified detail on this provider is limited, so the assessment remains qualitative. It operates an online application process and maintains U.S.-based operations. Its positioning centers on accessible eligibility for small firms that need flexible working capital without pursuing a large installment facility. For context on how revolving facilities differ from installment debt, see What Is An Unsecured Business Line Of Credit, And Where Can You Get One?. Owners should confirm current limits, draw fees, and repayment terms directly before layering this line with other debt.
The tradeoffs are structural. A revolving line is not designed for large, one-time capital projects, and repeated draws can create persistent carrying costs when balances are not cleared. As a single-product specialist, Headway Capital does not provide the broader hybrid package offered by a full broker. Its value is more precise: it gives steady businesses a reusable cushion instead of a bulk infusion.
Pros
- Revolving structure fits recurring short-term capital gaps and cash flow smoothing
- Online application supports convenient access for busy owners
- Accessible eligibility positioning for small firms seeking flexibility
- Pairs well with term loans by separating ongoing needs from fixed investments
Cons
- Limited verified product detail requires direct confirmation of terms and limits
- Revolving credit is not suited to large, one-time funding needs
- Single-product focus means owners must source other stack layers elsewhere
Best For: Small U.S. businesses that want a flexible revolving line for repeatable gaps while using separate products for larger term investments.
#4. Enterprise Business Funding – Best For Multi-Product Brokered Packages Including Factoring
Enterprise Business Funding offers the broadest product selection in this review. Founded in 1997 and headquartered in Encino, California, it operates as a broker that packages multiple instruments into one coordinated solution. Brokered products include business loans, lines of credit, SBA loans, factoring programs, purchase order funding, contract funding, trade finance, equipment financing and leasing, and short-term programs. That range makes it one of the few entries able to assemble factoring or purchase order layers alongside traditional debt.
The firm reports a small team of two and describes its history in terms of billions of dollars funded across industries. That language should be read as the company’s own characterization rather than independently verified volume. It offers secure file transfer and a streamlined application process for U.S. borrowers. For complex needs, such as combining SBA debt for stability with factoring for receivables acceleration, a broker model can reduce shopping time and help align timing across lenders.
The usual broker tradeoffs apply. Rates and terms are set by third-party lenders, not the broker, so costs and approval standards vary by matched product. A two-person operation may face capacity constraints compared with larger online lenders, while businesses seeking instant online decisions may find the consultative process slower. Public materials also provide limited eligibility detail, so owners should request written term sheets for each layer.
Pros
- Widest product breadth in this review, including factoring, purchase order funding, and trade finance
- Operating history since 1997 indicates longevity in alternative and brokered finance
- Covers nontraditional instruments rarely offered by single-product online lenders
- Suited to complex stacks that mix SBA loans with alternative products
Cons
- Very small team may limit capacity and turnaround during peak demand
- Broker model means pricing depends on third-party lenders
- Less suited to owners who need instant automated online decisions
- Limited public detail on minimum eligibility standards
Best For: Established U.S. firms that want one broker to coordinate a multi-product hybrid package, especially when factoring or specialized asset finance is required.
#5. Kiva – Best For Zero Percent Crowdfunded Microloans With No Collateral
Kiva occupies the low-cost micro layer of a hybrid stack. It provides zero percent interest loans with no fees, no collateral requirement, and no minimum credit score. Funding comes from a community of individual lenders rather than a bank balance sheet. The U.S. business program is active, and eligibility explicitly includes gig-economy operators such as hosts and drivers, alongside storefronts, service firms, and qualifying nonprofits.
The mechanics differ from conventional online business loans. Campaigns must attract community backing, so funding is neither guaranteed nor instant. Disbursement and repayment require a PayPal account, while nonprofits must demonstrate donation revenue from the past 12 months. Amounts remain at microloan scale, limiting their role to smaller needs such as starter inventory, minor equipment, or a first marketing test.
That limitation also defines Kiva’s place within hybrid business funding. A zero percent microloan can cover a small, defined use at the lowest possible cost, while a larger term loan or line provides scale. Owners should plan the sequence, using Kiva when patience is possible and reserving faster, higher-cost capital for time-sensitive gaps. The lack of collateral and credit floors makes it the most accessible entry point on this list for early-stage borrowers.
Pros
- Zero percent interest with no fees offers the lowest cost of capital in this review
- No collateral and no credit score minimum widen access for new or thin-file borrowers
- Useful as a small, low-cost layer alongside larger commercial products
- Includes nonprofits and gig workers often excluded from traditional lending
Cons
- Microloan amounts cannot support large capital projects
- Crowdfunded model means timing varies and funding is not assured
- PayPal account requirement adds a minor operational step
- Nonprofits must show 12 months of donation revenue to qualify
Best For: U.S. micro-businesses, early-stage ventures, nonprofits, and gig operators seeking a small zero percent community loan to complement larger stack layers.
#6. Fund My Biz – Best For Startups And Asset-Based Or Plan-Based Exceptions
Fund My Biz addresses cases that standard underwriting rejects. Founded in 2022 and based in Hewlett, New York, it operates as a broker with a network described as more than 350 lenders and hedge funds across the United States. Its main difference is a willingness to consider businesses with negative cash flow by underwriting on assets or a forward-looking business plan instead of trailing profitability alone.
No minimum or maximum dollar amount is stated, and funding can occur in as little as three business days once a match is found. That combination helps pre-profit startups, turnaround firms, and businesses with unconventional financial profiles secure a foothold layer that can later be refinanced or supplemented. As a broker, Fund My Biz matches borrowers to third-party terms rather than setting rates itself, so the final cost depends on the assigned lender and risk grade.
Its short history and limited public detail warrant caution. A 2022 founding date gives it a shorter operating record than most entries here. The absence of stated size ranges makes planning more difficult, and established firms seeking large structured facilities may find more specialized providers elsewhere. For its intended niche, asset-based and plan-based flexibility fills a gap that many fast business funding sources ignore.
Pros
- One of few brokers that explicitly considers negative cash flow profiles
- Network of more than 350 lenders and funds improves match odds for unusual cases
- Asset-based and plan-based underwriting supports startups without trailing profit
- Funding in as little as three business days once matched
Cons
- Founded in 2022, so operating history is limited
- Broker model leaves rates and terms to third-party lenders
- No stated minimum or maximum creates uncertainty around loan size
- Less suitable for established firms seeking large structured facilities
Best For: Early-stage U.S. businesses with negative cash flow or limited history that need an exception-based approval to start or stabilize a hybrid plan.
#7. iBusiness Funding – Best For Longer-Term Online Term Loans With Established Infrastructure
iBusiness Funding provides the longer-term installment anchor for owners who prefer a digital process backed by a larger organization. Founded in 2015 and headquartered in Fort Lauderdale, Florida, it reports more than 350 employees. That represents substantially larger operational infrastructure than most specialists on this list. Its focus is online term loans for U.S. small businesses.
Within a stack, a longer-term loan creates predictable scheduled payments for a defined investment such as expansion, renovation, or bulk inventory with a multi-month payoff. That stability contrasts with daily-remittance MCA products and revolving draws, allowing owners to separate durable investments from volatile short-term needs. A larger team can support underwriting, servicing, and customer assistance at scale, which some borrowers prefer over boutique funders.
Verified product detail beyond those fundamentals is limited, so pricing, amounts, and eligibility should be confirmed directly. It is not a broker and therefore offers less breadth than multi-product intermediaries. Firms in high-risk or severely cash-constrained positions may need a specialist for the urgent layer, then use this type of term loan for the steadier core.
Pros
- Team of more than 350 suggests substantial support, underwriting, and servicing capacity
- Operating history since 2015 provides a decade of market presence
- Online application fits owners who prefer digital-first borrowing
- Longer-term structures complement short-term MCA or line layers in a stack
Cons
- Limited verified detail on rates, amounts, and thresholds requires direct confirmation
- Direct-lender focus means less product breadth than full brokers
- Less suited to high-risk or deeply cash-flow-challenged borrowers
- No verified pricing to compare with SBA or secured bank alternatives
Best For: U.S. small businesses seeking a longer-term online installment loan from a mid-size lender to stabilize the core of a hybrid funding plan.
Frequently Asked Questions
What Is A Hybrid Business Loan And How Is It Different From A Traditional Business Loan?
A hybrid business loan is not a single standardized product. It describes a strategy that combines two or more funding instruments to cover different needs at the same time. Examples include an unsecured term loan for immediate working capital paired with a business line of credit for recurring gaps, or an SBA loan for long-term growth paired with invoice factoring for receivables timing. A traditional business loan is one instrument with one structure, repayment schedule, and underwriting framework. The hybrid approach recognizes that no single product serves every stage of the cash cycle equally well. Owners choose each layer for a defined job, then manage the total repayment burden so the layers work together rather than compete with one another.
How Can I Structure A Hybrid Funding Stack For Short Term And Long Term Needs?
Start by separating uses according to timing and certainty. Assign fast, no-collateral capital to urgent short-term needs such as payroll coverage or a time-sensitive inventory purchase. Revolving credit can handle repeatable gaps that return each month, while slower, lower-cost products such as SBA loans or equipment finance are better reserved for durable investments with multi-year payoffs. Keep repayment frequencies compatible, since daily MCA remittance combined with monthly term payments can strain the same cash flow. Document the total cost of each layer, confirm whether any lender restricts additional debt, and add layers in sequence so performance can be monitored.
Which Hybrid Business Funding Options Work With Bad Credit Or No Collateral?
Several options may work, but accessibility usually involves a tradeoff in cost, size, or speed. No-collateral business loans from online lenders remove the asset requirement, although they typically cost more than secured alternatives. MCA products assess receivables strength rather than relying only on perfect credit, but frequent remittance can raise the effective cost. Crowdfunded microloans through community models may offer zero percent interest with no credit floor, though amounts are small and funding takes time. Startup-friendly brokers may underwrite using assets or a business plan despite negative cash flow. Owners with challenged credit should build the smallest viable stack, verify every fee in writing, and plan to refinance expensive layers if performance improves.
How Quickly Can I Access Funds Through An Online Unsecured Small Business Loan?
Timing varies by lender, documentation, and underwriting method. Online unsecured products are generally faster than branch-based secured loans because they use digital applications, bank and revenue verification, and centralized review. MCA decisions can occur in hours, with funding in one to two days, while standard online term loans and lines often take several business days from approval to cash in the account. Brokered packages and SBA-linked layers take longer because they require third-party approvals. To reduce delays, prepare bank statements, revenue evidence, identification, and a clear use of funds before applying, then confirm the funding timeline and disbursement method in advance.
A Measured Path To A Stronger Funding Mix
What do I need to qualify for $200,000 through a hybrid funding approach? There is no universal standard because each provider evaluates its own part of the package. Expect reviews of time in business, documented revenue, cash flow consistency, credit history, existing obligations, and the proposed use of funds. Providers may request bank statements, tax returns, financial statements, ownership details, and debt schedules. The combined payments or remittances must fit projected cash flow, and one agreement may restrict additional financing.
What is the monthly payment on a $50,000 unsecured business loan? A reliable payment cannot be stated without the term, annual percentage rate or other pricing structure, fees, and payment frequency in the written offer. Some loans use monthly installments, while other funding arrangements collect daily or weekly payments and may quote a factor rate instead of an APR. Use the principal, full term, disclosed interest or total payback, and all fees from an actual offer to calculate and compare the payment.
What do I need to pursue $500,000 through a hybrid funding approach? A larger request generally calls for stronger documented cash flow, a longer operating record, and more complete financial statements, although each provider sets its own standards. A business may combine products for separate uses, such as a term loan for a defined investment and a line of credit for recurring working capital. Providers typically assess revenue stability, repayment capacity, credit, existing debt, and any assets or receivables involved. Confirm that each agreement permits additional financing and that the combined payment schedule remains affordable.
A deliberate mix can work better than one rushed loan when cash needs arrive on different timelines. Unsecured capital can address urgent needs, revolving lines can smooth recurring gaps, and specialized or lower-cost facilities can support larger investments. fundivi is one starting point to evaluate alongside structurally different alternatives, subject to confirming its current terms.